
Financial planning for veterans and military families
Retired pay, a VA rating, the TSP and TRICARE all follow you out of the military, and a civilian job adds its own paycheck and 401(k) on top. We help veterans in Columbus and across Ohio fit all of it into one plan. One of our partners is a Marine veteran who built his own VA claim, so we know this paperwork from your side of the table.
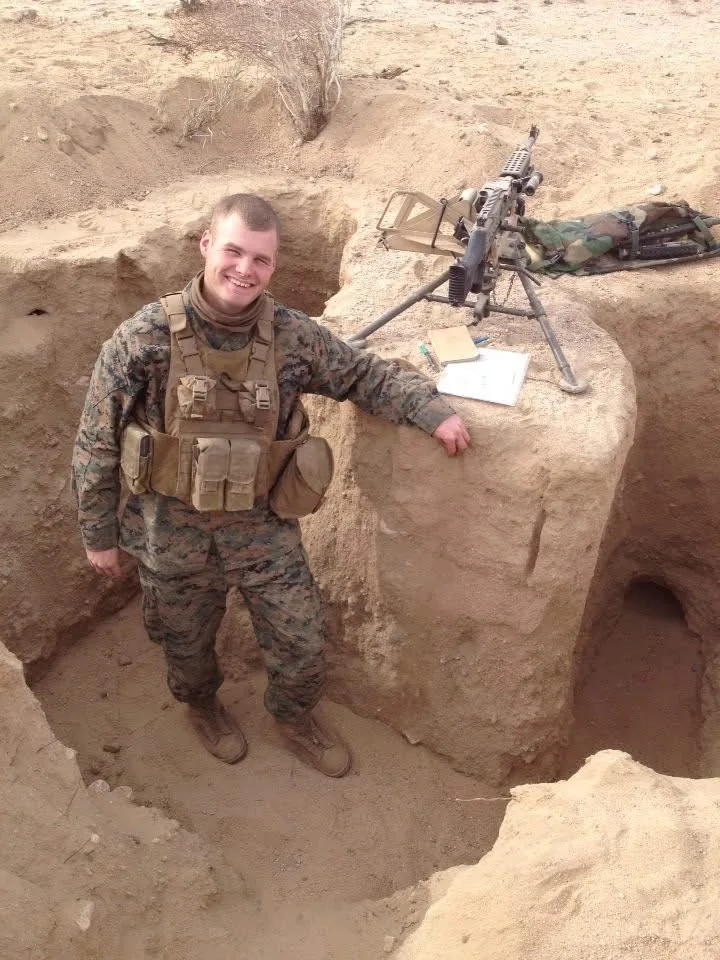
I filed my own VA claim with almost nothing in my records.
I served in an artillery battery with 1st Battalion, 11th Marines. In my unit, nobody went to medical unless something was broken, so when I got out my records showed almost nothing. I figured disability was for guys with combat injuries, and I waited ten years to file.
When I finally did, I built the claim myself, one condition at a time, with buddy statements from Marines I served with and a doctor's opinion tying each injury back to service. I wrote up the whole process in How I Built My VA Disability Claim With Almost No Medical Records.
Today I'm a Partner and Private Wealth Advisor at ClearMind Capital. When a veteran sits down with us, we start with the DD-214, the VA letter, and the TSP statement, and build the plan from there.
Shane Duckworth | Partner, Private Wealth Advisor | U.S. Marine Corps veteran
Leaving the military comes with a stack of decisions, and a few of them have deadlines that pass before your last day in uniform. Others, like your VA claim, your TSP, and your health coverage, keep mattering for decades. We help veterans and military families get the order right and build one financial plan around the benefits they earned. Every figure below is for 2026 unless noted.
Decisions to make before you take off the uniform
- Survivor Benefit Plan. SBP pays your spouse up to 55% of the base amount you choose after you die. The premium is generally 6.5% of that base, taken from retired pay before tax. You elect it at retirement, full coverage is the default, and covering your spouse for less takes their written consent. Decline it, and you generally can't add that spouse later. Premiums stop once you've paid 360 months and reached age 70.
- GI Bill transfer. You can move Post-9/11 GI Bill months to a spouse or child only while you're still serving, with at least 6 years in and an agreement to serve 4 more. Once you're out, the option is gone.
- Life insurance. SGLI ends after you separate. You can convert to VGLI within 1 year and 120 days, and if you apply within 240 days there are no health questions. Coverage goes up to $500,000, capped at the SGLI amount you had. With any service-connected rating, even 0%, VALife offers up to $40,000 of whole life coverage with guaranteed acceptance if you apply by age 80.
- Your VA claim. Benefits Delivery at Discharge lets you file 180 to 90 days before you separate, so a decision can come sooner after you're out.
We put these on one timeline built around your separation or retirement date, so none of them gets decided by default.
Your VA rating and what it pays
VA disability pay is tax-free and arrives every month. For a veteran with no dependents, it's $180.42 a month at 10%, $1,132.90 at 50%, and $3,938.58 at 100%, and it rises each year with the Social Security cost-of-living adjustment (2.8% for 2026). Ratings combine with the VA's whole person math, so 50%, 30%, and 20% come to 70%. Your rating also sets your VA health care costs. At 10% or higher there are no copays for VA inpatient or outpatient care, and at 50% or higher you're in Priority Group 1 with no medication copays.
Start with an intent to file. It gives you one year to submit the full claim and can set the date your benefits begin. VA-accredited Veterans Service Officers help for free, and every Ohio county has a Veterans Service Office. In Franklin County it's the Veterans Service Commission at Memorial Hall, 280 E. Broad St., (614) 525-2500. Federal law bars charging a fee to help with an initial claim, so be wary of anyone who asks for one.
ClearMind Capital doesn't file claims or represent anyone before the VA. Our part starts with the decision letter: what the rating does to your monthly income, health care costs, property taxes, and insurance options.
Military retired pay, CRDP, and your TSP
Retired pay is a multiplier times your years of service times your retired pay base, the average of your highest 36 months of basic pay. High-36 uses 2.5% a year and the Blended Retirement System uses 2.0%, so 20 years pays 50% or 40% of that base. BRS retirees also decide at retirement whether to take a lump sum of 25% or 50% of the discounted value of their retired pay, in exchange for a smaller check until full Social Security age. That trade is permanent, and it deserves a real comparison before you sign.
With 20 or more years and a rating of 50% or higher, Concurrent Retirement and Disability Pay lets you collect both in full. Below 50%, retired pay is reduced dollar for dollar by your VA pay, though the VA portion is tax-free. Combat-Related Special Compensation is a separate program for combat-related disabilities, and you can receive CRSC or CRDP, never both, so the choice is worth running the numbers on. The Major Richard Star Act would extend concurrent receipt to veterans medically retired with combat-related injuries before 20 years. It has strong support in Congress and had not become law as of this writing.
Your TSP can stay where it is after you separate. The C Fund's expense ratio was 0.035% for 2025, about 35 cents a year per $1,000, so compare your new plan's costs before rolling anything out. Since January 28, 2026, the TSP also allows Roth in-plan conversions. Shane covers how these pieces fit with a civilian job in How Military Retirement Benefits Work With a Civilian Job and a 401(k).
Starting a civilian job
The TSP and your new employer's 401(k) share one $24,500 limit on your own contributions for 2026 ($8,000 more at 50 or older, or $11,250 if you turn 60 to 63 this year). Your new payroll system has no idea what went into the TSP, so you have to track it. Put $9,000 in the TSP before separating in May and you have $15,500 of room left in the new plan. Your employer's match doesn't count toward the limit.
Military retirees can keep TRICARE alongside an employer health plan, and TRICARE pays after the employer plan. 2026 retiree enrollment fees run from $186.96 a year for an individual on TRICARE Select in Group A to $1,191 for a family on Select in Group B. At 65, TRICARE For Life requires Medicare Part A and Part B, and the timing gets tricky if you're still working with employer coverage. We map that out well before your 65th birthday.
Ohio benefits that are easy to miss
- State income tax. Ohio lets you deduct military retirement pay included in your federal adjusted gross income, so it isn't taxed at the state level. VA disability pay isn't taxed federally or by Ohio.
- Property tax. Ohio's homestead exemption for disabled veterans takes part of your home's value off the tax rolls if the VA has given you a total disability rating for a service-connected condition, including individual unemployability. Franklin County lists $58,000 of value exempt for tax year 2025, and the state adjusts the amount every year. A qualifying surviving spouse can keep it. You apply through your county auditor.
- College. The Ohio GI Promise gives qualifying veterans, spouses, and dependents in-state tuition at Ohio public colleges once they've made Ohio home. For children of deceased or severely disabled Ohio veterans, the War Orphans and Severely Disabled Veterans' Children Scholarship covered 77% of tuition and fees at Ohio public schools for 2025-26.
- Local help. The Ohio Department of Veterans Services is at 877-OHIO-VET (877-644-6838), and your County Veterans Service Office can walk you through state and county programs.
Buying a home with a VA loan
Eligible borrowers with full entitlement can buy with no down payment and no VA loan limit, though the lender still checks your income and credit. First use with less than 5% down carries a 2.15% funding fee, and veterans receiving VA disability compensation are exempt from it. On a $350,000 loan, that exemption is worth $7,525 at closing.
For military spouses
Under the Military Spouses Residency Relief Act, as expanded in 2022, a spouse can choose the service member's state of legal residence for state income tax, which can matter a lot after a move to or from Ohio. A spouse who isn't working can still fund an IRA based on the working spouse's income. And because SBP, VGLI, and the GI Bill transfer all affect the spouse directly, we want both of you in the meeting.
Austin Wolfe, who leads our workplace retirement practice, serves in the U.S. Army. If you own or run a business and have questions about your company’s 401(k), he’s the one to talk to.
What this can look like
Illustrative examples, not actual clients, and not a promise of results.
The May separation
A Marine separating in May has put $9,000 into the TSP and starts a civilian job in June. We set the new 401(k) contribution so the year's total lands at $24,500, compare the two plans' costs, and leave the TSP where it is until there's a reason to move it.
The 20-year retirement
A soldier retiring at 20 years under High-36 is married and has to elect SBP. We compare full SBP coverage with buying more life insurance, using both spouses' ages and the family's other savings, so the spouse signs off knowing exactly what the choice means.
The rating that changed the budget
A veteran's combined rating goes from 40% to 70%, and tax-free VA pay rises from $795.84 to $1,808.45 a month (2026 rates, no dependents). The extra income lets them raise their 401(k) contribution and add a Roth IRA from their civilian salary.
Where we start
Every family we work with starts the same way. You pick the two money questions on your mind, we answer those first, and the rest of your plan keeps running in the background. See the Clarity Cards and pick your two.
Why fee-only and fiduciary matters
Fee-only means we are paid by you, never through commissions or product sales, so the advice stays about you. Fiduciary means we are legally bound to act in your best interest, at all times. We work with clients in Columbus, across Ohio, and nationwide, and everything can be done virtually.
Common questions
Do you work with veterans outside Columbus?
Yes. We're based in Columbus and work with veterans and military families across Ohio and nationwide, usually over Zoom.
Can ClearMind Capital help me file my VA disability claim?
No. ClearMind Capital isn't a VA-accredited representative and doesn't prepare or file claims. For free help, contact a VA-accredited Veterans Service Officer or your County Veterans Service Office. Shane wrote up the process he used for his own claim on Clarity Corner, and we help with the financial planning around your rating.
Is military retirement pay taxed in Ohio?
No. Ohio lets you deduct military retirement pay that's included in your federal adjusted gross income. It's still subject to federal income tax.
Is VA disability pay taxable?
No. VA disability compensation isn't included in federal gross income, so it isn't taxed federally or by Ohio. It also doesn't count as earned income for IRA contributions.
What does the Survivor Benefit Plan cost?
The premium is generally 6.5% of the base amount you choose, taken from retired pay before tax, and the plan pays your survivor up to 55% of that base. You elect it at retirement, and choosing less than full spouse coverage requires your spouse's written consent.
Should I roll my TSP into an IRA or my new 401(k)?
You don't have to move it. The TSP stays put after you separate and its fund costs are among the lowest available. A rollover can make sense for broader investment choices or to consolidate accounts. We compare costs, fund options, and withdrawal rules before anything moves.
When does a VA rating make VA health care free?
With a rating of 10% or higher, you pay no copays for VA inpatient or outpatient care. At 50% or higher you're in Priority Group 1, which also removes medication copays. Care for a service-connected condition has no copay at any rating.
Let's line up your military benefits with the rest of your plan.
This page is general information for people exploring our services and is not investment, tax, or legal advice or a recommendation for any specific person or situation. The examples are illustrative, are not based on actual clients, and are not a promise of results. Strategies such as S-corp elections, backdoor and mega-backdoor Roth contributions, equity-comp decisions, and deferred compensation depend on your specific situation and current law, so confirm the details with a qualified professional before acting. ClearMind Capital LLC is a registered investment adviser; registration does not imply a certain level of skill or training. Past performance is not indicative of future results.
