Running the business is enough. Your 401(k) shouldn't feel like a second job.
We help shape your 401(k) around what your business is trying to accomplish, and help your employees use it the right way.
Does your company offer a 401(k) today?
No plan documents needed.
The responsibility you may not know you have
A 401(k) is one of the most regulated things a business offers. Federal law expects whoever oversees the plan to:
- Put employees’ interests first
- Follow a careful, consistent process
- Keep fees reasonable for what you get
- Offer a sensible mix of investments
- Run the plan the way its documents say
You know your business, your people, and where you’re headed. We shape your plan around that, backed by a process and a record you can stand behind.
The four pillars we review every year
Pick a pillar to see what goes into it. All four stand on your plan’s written record.
Built on your plan’s governance record
- Investment Policy Statement
- Meeting agendas & minutes
- Annual Plan Review report
- Fee benchmarking
- Education activity log
- Action item tracker
Fiduciary Governance & Oversight
Can you show how plan decisions were made?
Everyone knows who decides what, and every decision gets written down with the reason behind it.
- Clarify roles and responsibilities for your plan
- Set up a review calendar and documentation standards
- Keep you current on rule changes that affect your plan
- Benchmark fees and review your service providers
Investment Oversight
Is the lineup still right for your team?
Your team relies on these options for decades, so we review them each year against a written policy.
- Put a written investment policy in place
- Review the lineup against that policy each year
- Check the default option still fits your workforce
- Bring clear, data-backed options when a change is needed
Plan Design Optimization
Is the plan built to help people save?
Enrollment, the match, and the defaults decide how many people save and how much.
- Review eligibility, enrollment, and escalation features
- Compare your match to similar employers
- Flag new options and tax credits from recent legislation
- Explore ways for owners to save more, including cash balance plans
Participant Outcomes
Are your people on track?
A plan only works if people use it, so we track whether your team is taking part and saving enough.
- Track participation and savings rates across your team
- See who is saving enough to get the full match
- Deliver an annual employee education program
- Measure what changes year over year
From the first call through every year after
A conversation
We learn about your business, your team, and what you want the plan to do.
A starting point
Have a plan? Your ClearMind 401(k) Scorecard shows where it stands in about a minute. Starting one? A few questions shape our first conversation.
A foundation
We set up the roles, investment policy, and review calendar your plan runs on.
An annual rhythm
A full Annual Plan Review, a written report, and employee education every year.
A growing record
Each year adds to a written history of how your plan has been run.
Your plan has a solid base, with several items worth a closer look.
Filing Signer25% weight51Priority
Shows who carries the legal duty for running the plan.
The company runs the plan itself, and the filing shows open items. The people in charge can be personally liable for those.
From the filingCompany is its own plan administrator
Auto Features10% weight57Priority
Shows how the plan lines up with industry and legislative trends.
Employees have to sign themselves up. Nationally, 94% join when they’re enrolled automatically, compared with 64% when they have to opt in.
From the filingDefault investment yes; no auto-enrollment code
Corrective Refunds20% weight68Monitor
Any score below 100 means refunds, a sign of failed IRS fairness testing.
Money had to be sent back out of the plan, usually after a failed IRS fairness test. Whoever got it, often owners or top earners, owes tax on it.
From the filing$1,400 refunded; no plan loans
Audit Threshold15% weight80Strength
Shows if the plan needs an independent audit, is close, or is missing one.
You’re well under 100 people with balances, the point where a plan can need a yearly independent audit, a cost that can run thousands of dollars.
From the filing66 with balances; about 14 former employees
Bond & Compliance30% weight97Strength
Regulators check these first when choosing plans to audit.
Your bond covers this year’s legal minimum. The plan has grown, so next year’s minimum is about $214,000, more than the bond you carry.
From the filing$200K bond vs. ~$214K next-year need
The plan’s story
Since 2012, you’ve helped your team plan for life after work. But 14 of the 66 people who could join haven’t started yet, and each year they wait is savings they won’t get back. You’ve built a foundation your team can lean on, and this story isn’t over. You still have two areas marked Priority that deserve a conversation.
What we are, and what we’re not
We work alongside the providers you already have.
We are
- Independent, fee-only retirement plan advisors
- The ones who prepare the analysis and keep the record
- The people who explain the rules so every decision makes sense
We’re not
- A recordkeeper or plan administrator
- A law firm or a tax preparer
- A payroll provider
- A product seller. We don’t earn commissions.
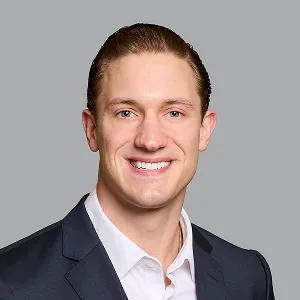
Austin Wolfe
Austin Wolfe works exclusively with employers on 401(k) plan design, fiduciary oversight, investment monitoring, and participant education. His clients are business owners who want to feel confident about the retirement plan they offer.
He came to the independent advisory side after time inside the institutional retirement-plan industry, consulting plan sponsors directly. He’s seen the operational and fiduciary headaches from the inside, which is why he can give honest, objective guidance without a product agenda.
Austin is also a former Army officer and fixed-wing pilot. Leading complex operations under pressure builds a certain kind of discipline, and it shows in how he runs a plan review.
He went to Michigan State, studied Criminal Justice, and played Division I football as a wide receiver. Outside of work, he spends time with his wife Brittany, their son Callum, and their dogs, and gets outside whenever he can.
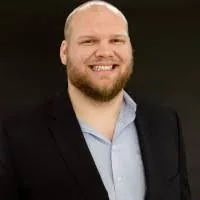
Joe Anderson
Joe is a Retirement Plan Advisor at ClearMind Capital (CMC), running the mechanics behind a defined contribution plan. Where Austin leads the advisory relationship, Joe makes the plan work: document and design decisions, recordkeeper and payroll coordination, annual compliance testing and notices, and the steady effort of getting more employees enrolled, contributing, and invested well.
Joe spent years alongside Austin on the institutional side of the 401(k) business, working between recordkeepers, payroll teams, and plan committees. The two of them came to the same conclusion: the only way to do the best work for a plan sponsor is to get away from the corporate friction. That is what CMC Workplace Retirement is, and the kind of experience we intend to give every business we work with.
Joe earned his degree from Ohio University and played Division I football there as an offensive lineman. He and Nick go back to their college days too, as brothers in Sigma Chi. At home, Joe and his wife Brooke have two daughters, Ava and Abby.
Questions owners ask us
Do I have to switch providers to work with you?+
No. We work alongside the providers you already have. Many engagements start with a ClearMind 401(k) Scorecard on your current plan, and switching is never a requirement.
Do I need to be a retirement plan expert?+
No. You bring knowledge of your business and your team. We bring the structure, the analysis, and the paperwork, and we explain each piece clearly so you can make informed decisions.
What size companies do you work with?+
Businesses of all sizes, including companies starting a plan for the first time.
What is the ClearMind 401(k) Scorecard?+
It’s a report card for your company’s 401(k). Find your plan, confirm it, and it scores five areas from the annual report your plan files with the Department of Labor: the fidelity bond and compliance answers, the audit threshold, automatic features, corrective distributions, and who signed the filing. You see your overall score right away, and Austin and Joe can walk you through what it means.
Do you give my employees individual investment advice?+
Our employee education is general: how the plan works, why saving matters, and basic investing concepts. It isn’t personalized advice about which funds to pick or how much to contribute.
Can owners save more than a 401(k) allows?+
Often, yes. For some owners, a cash balance plan alongside the 401(k) can allow much larger contributions. We look at this as part of plan design and coordinate with the specialists who set it up. See how cash balance plans work.
The ClearMind Workplace Retirement Newsletter
Plan rules, deadlines, and ideas for running a better 401(k), written for business owners.
You’re on the list. Watch your inbox for the next issue.
By subscribing, you agree to receive the ClearMind Workplace Retirement Newsletter by email. Unsubscribe anytime. See our Privacy Policy.
Let’s take a look at your 401(k)
Thirty minutes with Austin and Joe. You’ll leave with clear next steps and no obligation to switch anything.
Rather write? Email retirementplans@clearmind-capital.com.
This content is for informational purposes only and does not constitute investment, tax, or legal advice. ClearMind Capital LLC is a registered investment adviser. Registration does not imply a certain level of skill or training. Past performance is not indicative of future results. For more about our services, fees, and conflicts of interest, see our Form ADV Part 2A (CRD #334362).
